
-
Refinery Earns More in Third Quarter Than All of First Half as Margins Soar
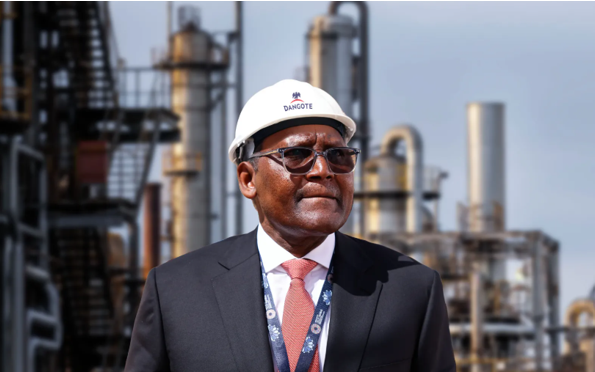
Dangote Petroleum Refinery & Petrochemicals FZE earned more in the third quarter than in the whole first half.
Its nine-month results give investors in Africa’s largest initial public offering (IPO) their clearest view yet of the plant’s earnings power, and they show the N525 offer price looking increasingly cheap.
Net income rose to $4.73 billion in the nine months to September, 2026, from a loss of $117.2 million a year earlier, the company said in an unaudited statement on October 13. Revenue rose 144% to $22.48 billion.
Earnings before interest, tax, depreciation and amortisation (EBITDA) rose to $5.52 billion from $627.6 million, and the EBITDA margin widened to 24.6% from 6.8%.
“Our third-quarter performance demonstrates the successful transition from commissioning and ramp-up activities to sustainable commercial operations,” Chief Executive Officer David Bird said.
A Record Quarter
Third-quarter net income alone was about $2.9 billion, 60% more than the entire first half, on MoneyCentral calculations. The quarter’s EBITDA margin was 34.1%, helped by record diesel and jet fuel margins, as the Iran war and Ukraine’s strikes on Russian refineries tightened global fuel supply.
Nine-month profit already exceeds CardinalStone Research’s full-year forecast of $3.8 billion.
If fourth-quarter profit stays close to the third-quarter run rate, MoneyCentral estimates full-year net income of about $7.5 billion, or roughly N10 trillion at N1,335.50 per dollar.
That would be equivalent to N80.7 a share on 124 billion post-offer shares.
At N525, the stock would trade at about 6.5 times earnings, and a 13 times multiple implies a rise to about N1,049 Per share upon listing.
MoneyCentral Thesis Confirmed
The figures support MoneyCentral’s Buy recommendation for the IPO and 12-month target of N1,020, set on September 21 using first-half earnings alone. The offer has been extended to October 27.
The thesis was that the refinery had left its costly commissioning phase and entered sustained high use, where fixed costs are spread over more barrels. The third quarter supports that: revenue increased to US$22.5bn in 9M 2026 from US$9.2bn in 9M 2025, reflecting improved refining activity and higher throughput.
On enterprise value, which adds debt and subtracts cash, the offer values the refinery at about $48.1 billion. That equals about 6.5 times prorated full-year EBITDA, down from about 9.5 times annualised first-half EBITDA when the offer opened.
Risks to Our Outlook
The 9Month results released by the Dangote Refinery are unaudited and include only headline figures. Third-quarter net income of $2.90 billion almost equaled EBITDA of $2.92 billion. In the first half, net income was about 70% of EBITDA, so the third quarter appears to have had unusually low depreciation, interest and tax, or one-off gains.
Part of the cash build may also reflect July’s $2.5 billion private placement, not just operations.
Also for margins to remain at third-quarter levels, it would depend on war-related supply disruption, which could be resolved quickly, post U.S elections, especially if the Democrats gain 1 branch of power.
The IPO prospectus guides to a 2026 gross refining margin of about $24.20 a barrel, far below recent levels. Sales into Nigeria may also incur higher taxes from 2028, when free-zone tax benefits on those sales may end.
 Follow the MoneyCentral Nigeria channel on WhatsApp: Click here!